
Meta options
Meta trades at 611.70; 30-day implied volatility is 41.8%, and the market prices a ±5.83% expected move into the 2026-11-13 expiry, 6 days out.
Cheap or dear right now
- Fairly priced: IV30 is within 1 point of 20-day realised volatility, so options are priced close to recent movement.
- Over the next 6 days (expiring 2026-11-13) the market prices a one-standard-deviation move of ±5.83%, about 35.67 points.
- Skew 5.2: puts are pricier than calls, so the market is paying up for downside protection.
- Put/call volume ratio 0.62: call volume clearly outnumbers puts.
Pricing across strikes
2026-11-13 expiry (6 days), spot 611.70. The further apart the two lines, the bigger the skew.
Implied volatility by expiry
Near-dated IV above far-dated (inverted) points to short-term event risk; the reverse suggests calm now and more movement later.
Where the open interest sits
Bar height is open interest; max pain is the strike that minimises the total value of expiring options.
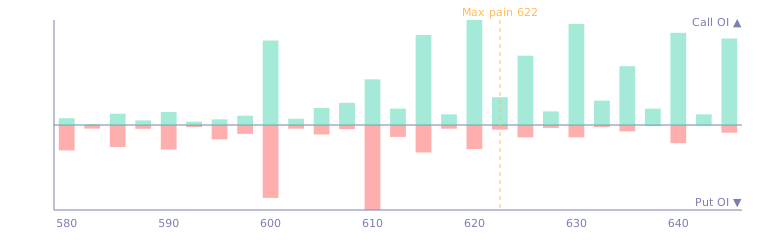
2026-11-13 expiry, five strikes either side of the money
IV is the implied volatility at that strike; OI is open interest.
| Call OI | Call IV | Strike | Put IV | Put OI |
|---|---|---|---|---|
| 547 | 47.1% | 600 | 47.0% | 2,102 |
| 40 | 46.8% | 602 | 46.7% | 107 |
| 110 | 46.5% | 605 | 46.3% | 274 |
| 144 | 46.2% | 608 | 46.0% | 118 |
| 296 | 45.9% | 610 | 45.9% | 2,451 |
| 106 | 45.5% | 612 ATM | 45.5% | 344 |
| 583 | 45.2% | 615 | 45.1% | 792 |
| 69 | 45.1% | 618 | 44.9% | 107 |
| 680 | 44.8% | 620 | 44.7% | 695 |
| 180 | 44.7% | 622 | 44.4% | 135 |
| 449 | 44.3% | 625 | 44.3% | 358 |
FAQ
Is the expected move a guarantee?
No. It is a one-standard-deviation move implied by at-the-money option prices — the market's current price for movement, not a forecast or a guarantee.
Why is IV rank empty?
IV rank needs a year of IV30 history. Our database records IV30 once a day and shows a value after 20 trading days; until then the page shows collection progress.
What does a positive skew mean?
25-delta puts carry a higher implied volatility than calls at the same expiry, so the market is paying more for downside protection — typical when hedging demand rises.
Can I trade straight off this page?
No. This is volatility and pricing information, not a buy or sell signal.
Data from CBOE delayed quotes (about 15 minutes behind), for information only and not investment advice. Options carry high risk and can lose the entire premium.