Weekly Market Recap: WTI Crude Falls 12.35%, Gold and Silver Rally, US CPI Eyed Next Week
WTI crude closed the week at 89.46, down 12.35% and the biggest mover among major markets, while gold and silver rallied and the dollar index edged higher. This recap covers global market performance for Nov 2 to Nov 8, the US October nonfarm payrolls result, and next week's China CPI, PPI and US CPI releases.
The week in context: crude slumps, metals and Hong Kong equities gain
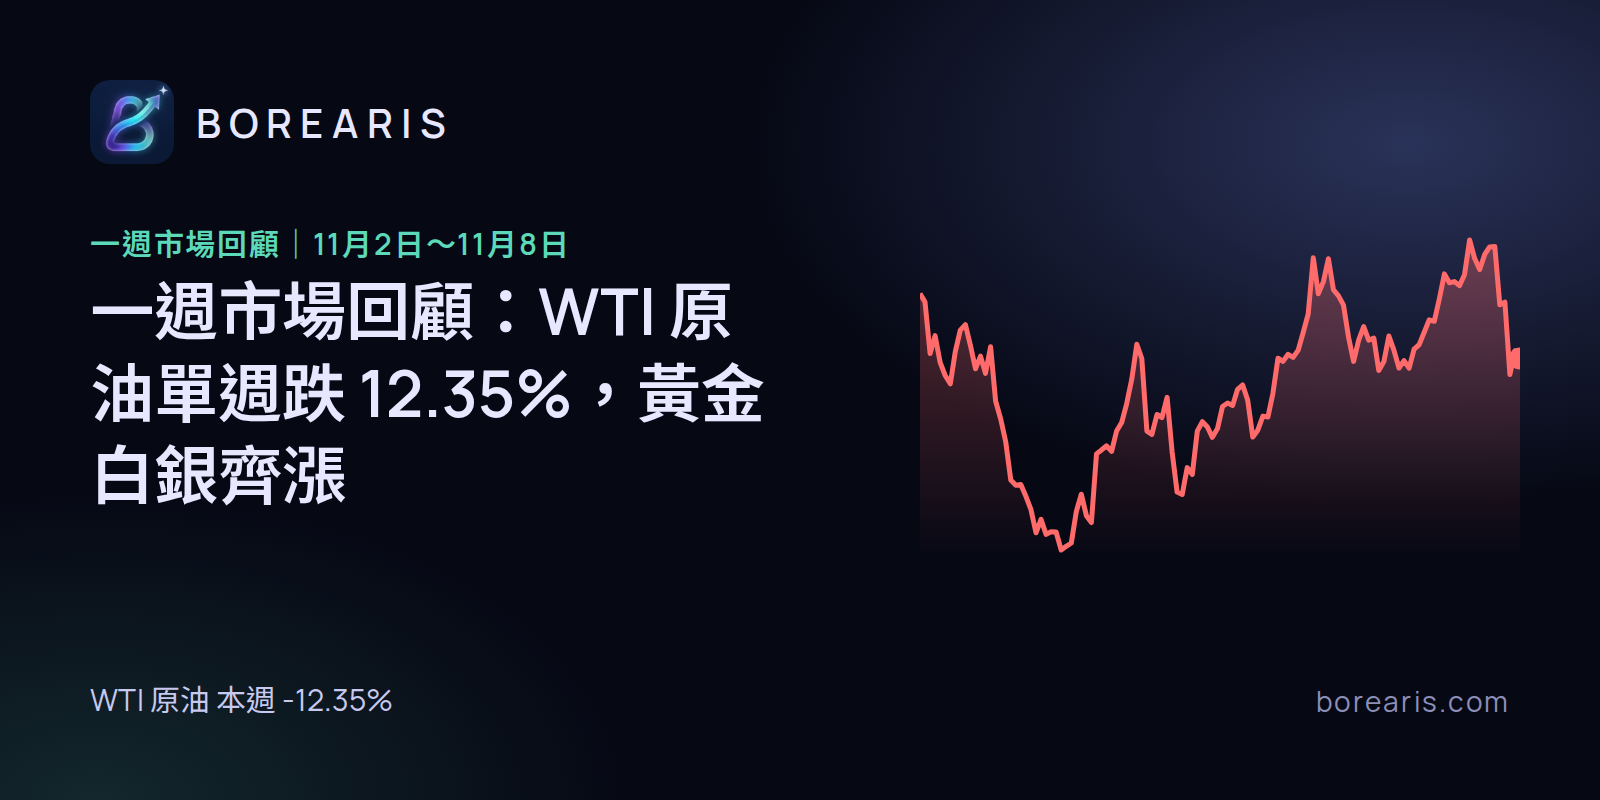
Global markets diverged in the week of Nov 2 to Nov 8, 2026. WTI Crude Oil (USOIL) closed at 89.46 versus 102.06 the prior week, a weekly change of -12.35%, the steepest decline among major markets. The Nasdaq 100 (NAS100) and S&P 500 (SPX500) also fell, down 4.96% and 2.68% respectively. On the other side, Silver (XAGUSD) rose 5.81%, the Hang Seng 50 (HK50) gained 5.09% and Gold (XAUUSD) added 5.08%, making them the week's relative outperformers.
Crude oil: the deepest weekly decline
WTI Crude Oil (USOIL) closed at 89.46, down from 102.06 a week earlier, for a weekly change of -12.35%. Weaker crude prices typically feed through to inflation expectations and energy equities. If next week's data show demand is not deteriorating further, oil could stabilise in a range, though direction will still depend on supply and demand headlines.
Precious metals: gold and silver move higher together
Gold (XAUUSD) closed at 4,071.00 versus 3,874.25 the prior week, up 5.08%, while Silver (XAGUSD) closed at 51.932 for a 5.81% gain. Both rising together often reflects shifts in safe-haven demand and real-rate expectations. If US CPI next week comes in above expectations, precious metals could see short-term volatility; key levels are worth watching on the Gold (XAU/USD) analysis page and the Silver (XAG/USD) analysis page.
FX: dollar index edges higher
The US Dollar Index (DXY) closed at 102.116, up 0.39% on the week. Among major pairs, EUR/USD (EURUSD) closed at 1.11392, down 0.14%; GBP/USD (GBPUSD) closed at 1.33428, down 0.31%; and USD/JPY (USDJPY) closed at 158.411, up 0.60%. With the dollar firm and non-US currencies mixed, FX volatility could pick up if next week's inflation data shift rate-cut expectations; see the US Dollar Index (DXY) analysis page and the USD/JPY analysis page.
Key data released this week
- US October nonfarm payrolls (thousands): expected 7万人, previous 2.9万人, actual 16.5万人.
The actual figure came in above both the forecast and the prior reading, pointing to a firmer labour market, which typically shapes views on the rate path. Whether CPI next week confirms that picture is the key question.
What to watch next week
- Nov 9, 09:30 China October CPI YoY, previous 0.9%.
- Nov 9, 09:30 China October PPI YoY, previous 5%.
- Nov 10, 12:02 China October imports YoY (USD), previous 31%; October exports YoY (USD), previous 36.3%.
- Nov 10, 21:30 US October core CPI YoY, previous 2.6%; October CPI YoY, previous 3.7%.
Separately, China's October foreign exchange reserves (USD 100 million) came in at 34051.8亿美元 versus a previous 34002.5亿美元. Event times and more entries are on the economic calendar, and trend shifts across major instruments can be tracked with swing signals. To follow next week's moves on the go, download the app.
Borearis Research Team · For information only, not investment advice. Trading involves risk.